 Written by: Content Team
Reviewed by: Hassan Rathore, CPA (Ex-PwC), Founder of NexusWorks
Last reviewed: 09 October 2026
The FICA tip credit is a federal tax credit under Internal Revenue Code Section 45B that allows eligible restaurant employers to claim certain employer-paid Social Security and Medicare taxes on employee tips.
The credit is not simply 7.65% of all reported tips. The calculation depends on which tips qualify, the employee’s direct wages, the Section 45B wage benchmark, and the employer FICA taxes attributable to those tips.
For qualifying food and beverage establishments, Section 45B uses the federal minimum wage rate that was in effect on January 1, 2007, resulting in a $5.15-per-hour benchmark. This is different from the current $7.25 federal minimum wage and the separate FLSA tip-credit rules. 26 U.S. Code §45B
This guide answers the key questions restaurant owners and finance teams have about the FICA tip credit: Who qualifies? Which tips count? How is the credit calculated? What is Form 8846 used for? And can a restaurant claim the credit for a prior year?
The FICA tip credit is a federal general business tax credit that allows an eligible employer to claim certain employer Social Security and Medicare taxes paid or incurred on qualifying employee tips.
In simplified terms, the calculation involves:
Qualifying Tips − Section 45B Wage Adjustment = Creditable Tips
The resulting creditable tips are then used to determine the employer’s allowable FICA tip credit under the applicable Form 8846 instructions.
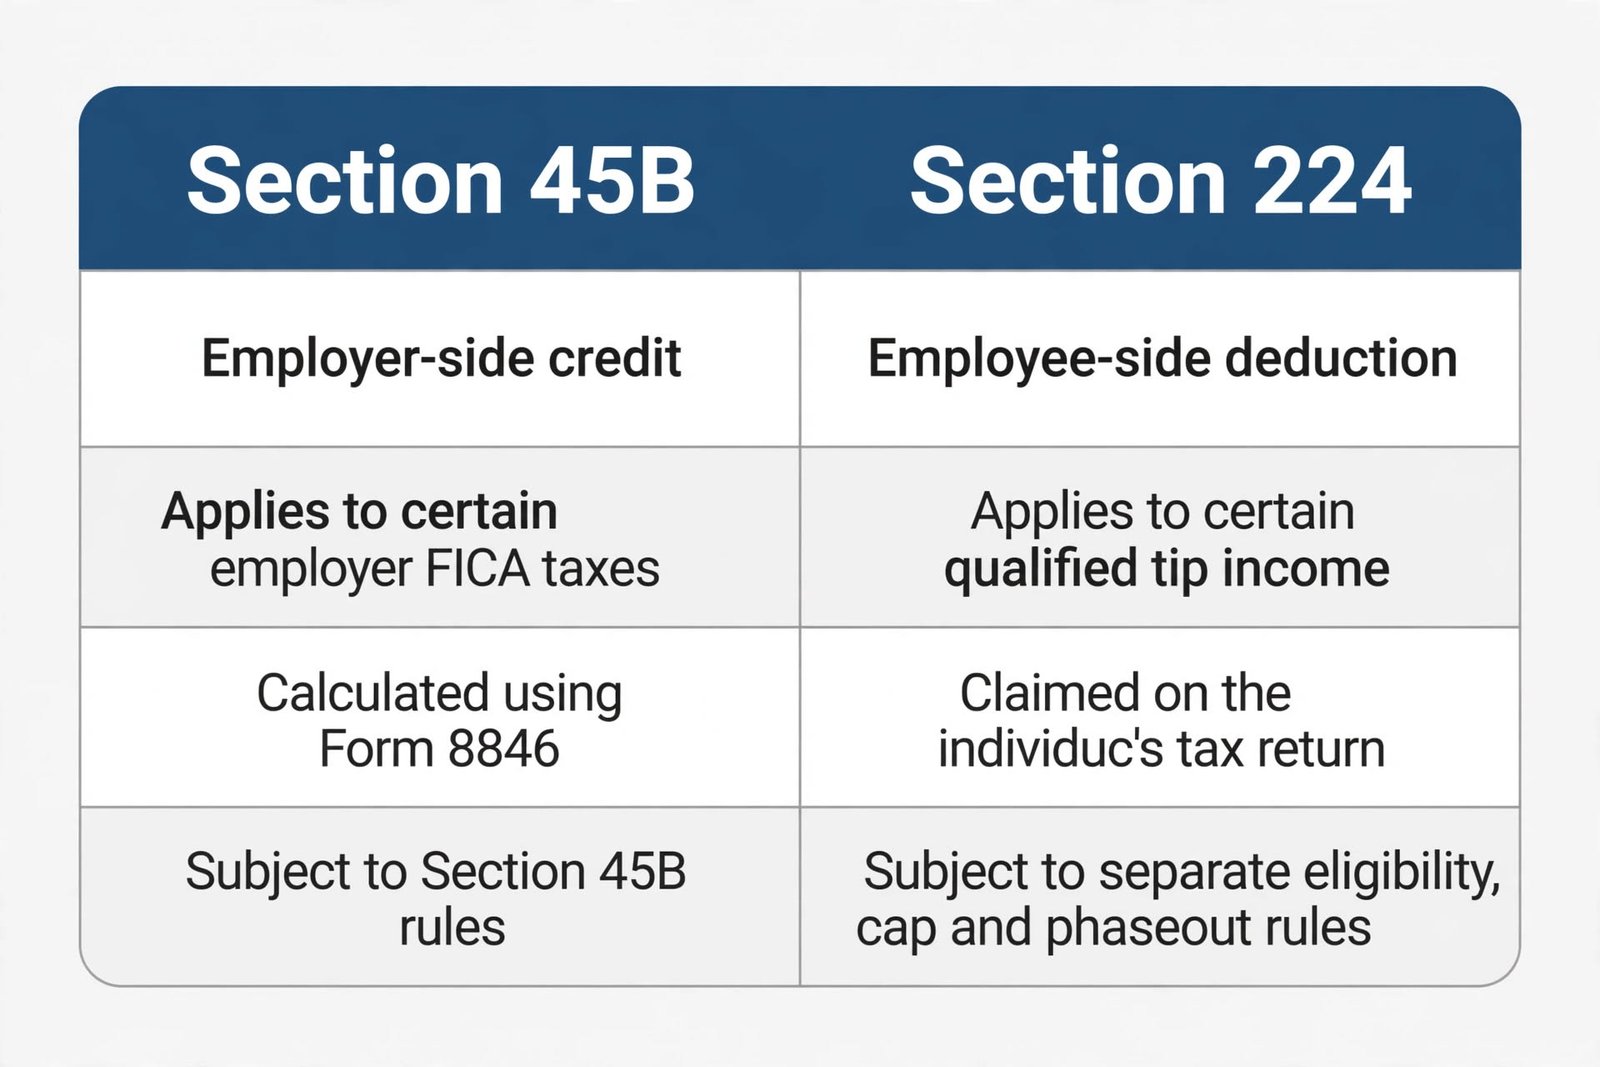
The credit belongs to the employer, not the employee. It is also separate from the employee-side qualified-tip deduction created under the 2025 tax law.
A restaurant generally must meet the statutory requirements for a food and beverage establishment, including that tipping employees who provide, deliver, or serve food or beverages is customary.
The credit generally relates to employer Social Security and Medicare taxes paid or incurred on qualifying employee tips. The restaurant’s tipping practices, employee duties, payroll records, and treatment of tip amounts can affect the calculation.
Having tipped employees does not automatically mean that every dollar of reported tips produces a credit.
Restaurants should review:
The calculation starts with qualifying tips on which the employer paid or incurred employer FICA taxes.
For qualifying food and beverage establishments, Section 45B uses the federal minimum wage in effect on January 1, 2007 as the relevant benchmark. That produces the $5.15-per-hour benchmark used in the Section 45B calculation. Section 45B Statutory Rules
Start with employee tip records and determine which tips were included in the employer’s Social Security and Medicare tax calculation.
Do not assume that the restaurant’s total POS tip amount is automatically the amount used for the credit calculation.
POS records, employee tip reports, payroll registers, and accounting records should reconcile so the restaurant can support the amounts reported on Form 8846.
The restaurant then considers the employee’s direct wages and hours against the applicable Section 45B wage benchmark.
For example, assume an employee:
Using the $5.15 benchmark:
100 hours × $5.15 = $515
The difference between the benchmark wages and direct wages is:
$515 − $375 = $140
Under this simplified example, the $140 wage adjustment reduces the amount of tips treated as creditable.
The employee has $450 in qualifying tips, with a $140 adjustment under the example above.
Therefore:
$450 − $140 = $310 creditable tips
This is a simplified illustration. The actual calculation should follow the applicable Form 8846 instructions for the tax year being claimed.
Using an illustrative combined employer FICA rate of 7.65%:
$310 × 7.65% = $23.72
Under the assumptions in this example, the resulting illustrative credit is $23.72 for that employee.
The actual credit should be calculated using the applicable Form 8846 instructions and the employee’s complete payroll and tip records.
No. A restaurant should not automatically multiply every employee’s annual tips by 7.65%.
The 7.65% employer FICA rate generally consists of:
The Social Security portion is subject to the annual Social Security wage base. For 2026, the wage base is $184,500. As a result, the calculation can depend on the employee’s cumulative wages and tips and whether the employee has reached the Social Security wage base during the year.
For restaurants with employees who reach the Social Security wage base, the employer should reconcile the employee’s year-to-date payroll and tip records before applying a blanket 7.65% calculation.
This is one of the most important distinctions in the entire calculation. The current federal minimum wage is $7.25, but Section 45B specifically provides a different benchmark for food and beverage establishments by referring to the federal minimum wage as it was in effect on January 1, 2007. That rate was $5.15. Therefore, the current federal minimum wage should not automatically be substituted for the Section 45B restaurant benchmark.
This also explains why the FICA tip credit should not be confused with the FLSA tip credit. The Department of Labor’s FLSA rules address minimum-wage and overtime obligations, including the separate tipped-employee framework. U.S. Department Of Labor: Tipped Employees Under The FLSA
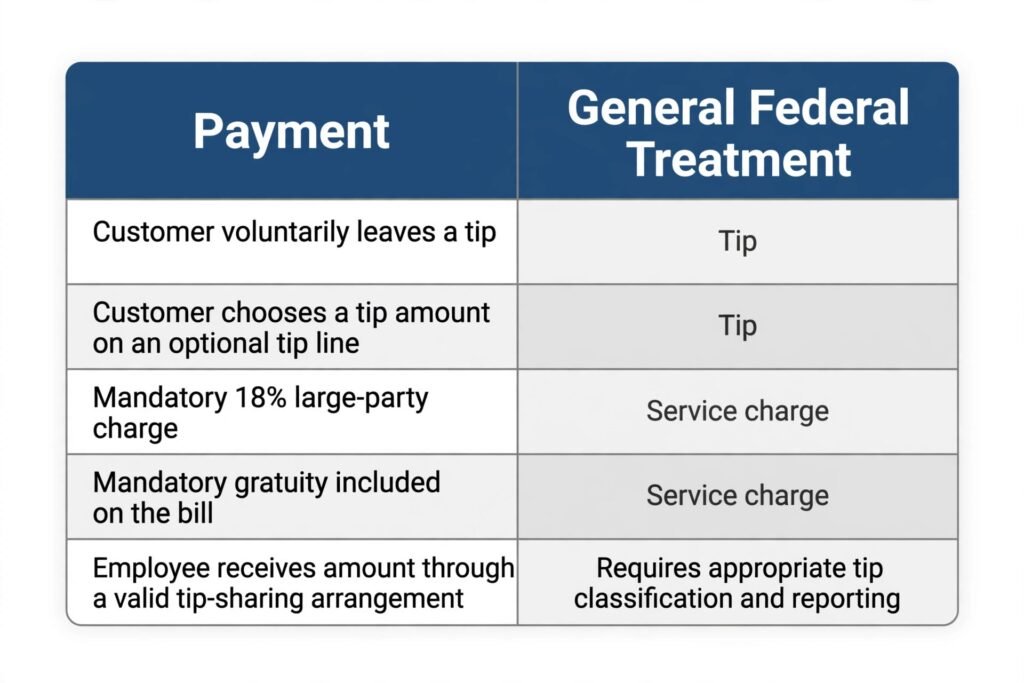
Generally, mandatory service charges are not customer tips. A true tip is a discretionary payment where the customer voluntarily decides whether to pay and determines the amount. A mandatory charge added to a customer’s bill is generally treated as a service charge and, when distributed to an employee, as wages.
For example:
The IRS specifically distinguishes mandatory service charges from voluntary tips and notes that service charges distributed to employees are generally treated as wages. IRS Tip Recordkeeping And Reporting Guidance. This distinction should be reflected consistently in the restaurant’s POS, payroll and accounting records.
Restaurants generally calculate the credit using Form 8846, Credit For Employer Social Security And Medicare Taxes Paid On Certain Employee Tips.
The practical process is:
Payroll And Tip Records → Form 8846 → Business Tax Return / General Business Credit Reporting
Form 8846 should be prepared using the instructions applicable to the tax year being claimed. The credit is part of the general business credit system, so the amount calculated on Form 8846 does not necessarily mean the entire credit can immediately reduce the current year’s tax liability. General business credit limitations and carryover rules may affect when the credit can be used. IRS General Business Credit Guidance
For restaurants reviewing previous returns, the relevant tax filing and amendment process should also be considered alongside the credit calculation. NexusWorks Tax Filing & Compliance Services
Potentially. A restaurant that discovers an eligible FICA tip credit was not claimed should review the relevant tax return, determine the correct credit amount, and establish whether an amended return or other corrective filing is available.
The review should be performed year by year, rather than assuming that every historical year remains open.
Before preparing an amended claim, verify:
A calculated credit is also not automatically the same thing as a cash refund. The restaurant’s overall tax position and applicable credit rules determine how much of the credit can actually be used.
No. The Section 45B FICA tip credit belongs to the employer. The separate qualified-tip deduction under Section 224 applies to eligible individuals receiving qualifying tips. They address different taxpayers and different tax consequences.
The employee deduction does not eliminate the restaurant’s payroll-tax obligations or automatically replace the employer’s Section 45B credit.
The strongest calculations begin with reconciled source data.
A restaurant should be able to trace the credit calculation back to records such as:
This is where accurate bookkeeping and payroll records become important. NexusWorks Bookkeeping & Financial Management Services. If POS data says one amount, payroll reports another, and the general ledger contains a third amount, the difference should be resolved before the credit is calculated.
The most common problems are usually calculation or classification issues rather than the basic concept of the credit.
Watch for:
For multi-location operators, the risk increases when payroll, POS and tax data are maintained separately by location or legal entity.
Start with the records, not the estimated tax benefit.
A practical review is:
For operators with multiple entities, locations or significant prior-year credits, integrating the review with broader tax planning and strategy can help determine how the credit fits into the business’s overall tax position. NexusWorks Tax Planning & Strategy
It can, particularly when payroll and tax reporting are handled differently across locations.
A multi-unit operator may need to reconcile:
For larger operators, the question becomes less about whether a single employee generated a credit and more about whether the organization’s financial systems consistently capture the information needed to identify and substantiate the credit.
That broader financial oversight can also make Fractional CFO support relevant when restaurant groups need better coordination between reporting, cash flow, tax planning and financial decision-making. NexusWorks Fractional CFO Services
For a 2026 review, focus on the rules that actually affect the calculation rather than adding a year simply for freshness:
The IRS has also published draft 2026 Form 8846 materials marked “DRAFT—NOT FOR FILING.” Restaurants should use the final form and instructions applicable to the return rather than treating a draft form as final.