Business
QuickBooks Payroll Setup Checklist
Before the first QuickBooks payroll, open your state withholding and unemployment accounts, collect W-4s and state forms, set…
READ MORE ● NexusWorks Team
Reviewed by a licensed CPA
Short answer: Start with today's bank balance, then list expected customer payments and every payment due, week by week, for the next 13 weeks. Find the week with the lowest closing balance. If it drops below about two payrolls, act now while you still have options.
“Am I going to run out of money?” is a question a lot of business owners type into a search bar late at night. The profit and loss report says the business made money. The bank balance says otherwise. Payroll is Friday.
The honest answer is that nobody can tell from last month’s numbers. You find out by looking forward, week by week. The tool finance teams use for this is called a 13-week cash flow forecast. It’s a spreadsheet, not software, and you can build a usable one in an afternoon.
Profit counts a sale when you invoice it. Cash counts it when the money lands. In between sit customers who pay in 45 days, inventory you paid for in advance, loan payments that never show up on the P&L, and a quarterly tax payment you forgot was coming. We go through the usual causes in why profitable businesses still run out of cash. The forecast is how you see them coming.
It’s one row per type of cash in or out, and one column per week for the next 13 weeks. Thirteen weeks is one quarter: far enough ahead to see trouble, close enough that your guesses are still decent. Each week you update the actual numbers for the week that just ended and roll the forecast forward by one week.
| Week 1 | Week 2 | Week 3 | … | |
|---|---|---|---|---|
| Opening cash | $42,000 | $38,500 | $51,200 | |
| Customer receipts | $18,000 | $31,000 | $9,500 | |
| Payroll and payroll taxes | ($14,000) | $0 | ($14,000) | |
| Rent | ($6,500) | $0 | $0 | |
| Suppliers | ($1,000) | ($18,300) | ($4,000) | |
| Loan payment | $0 | $0 | ($2,800) | |
| Closing cash | $38,500 | $51,200 | $39,900 |
Each week’s closing cash becomes the next week’s opening cash. The number you watch is the lowest closing balance in the 13 weeks, not the last one.
Use the actual balance across your operating accounts this morning, not the balance in your accounting software. If the two are far apart, your books need reconciling first.
Go through your open invoices and put each one in the week you expect the money, based on how that customer really pays, not your payment terms. A customer who always pays at 52 days goes in at 52 days. Add expected new sales separately and keep them conservative.
Payroll on its actual dates, rent, loan and lease payments, insurance, software subscriptions. These rarely move, which makes them the easiest part.
Open bills go in the week they’re due. Add expected new purchases, especially inventory.
Quarterly estimated taxes, annual insurance premiums, sales tax remittances, owner draws, equipment purchases, annual software renewals. These are the payments that turn a fine-looking month into a crisis. Our note on the quarterly estimated tax deadline is a reminder of one that catches many owners.
Look for the week with the lowest closing cash. If it drops below the cushion you’re comfortable with (many owners use two payrolls), you now have weeks to act instead of days:
If the forecast shows a gap you can’t close with the steps above, or you’re making payroll decisions from it every week, that’s the point where a part-time finance lead earns their fee. A fractional CFO builds and runs this forecast with you, ties it to your budget and taxes, and helps you have the bank conversation before you need the money.
Build a 13-week cash flow forecast. Start with today’s bank balance, add expected customer payments by week, subtract every payment due, and look for the week with the lowest closing balance.
Profit records sales when you invoice and costs when you incur them. Cash moves on different dates. Slow-paying customers, inventory, loan payments and tax payments can drain cash while the profit report still looks fine.
Thirteen weeks is one quarter. It’s long enough to spot trouble early and short enough that weekly estimates stay reasonably accurate.
Every week. Replace last week’s estimate with the actual figures, then add a new week at the end so you always see 13 weeks ahead.
Want a second pair of eyes on your numbers? Book a call and we’ll help you build your first 13-week forecast from your own data.
Keep reading
Business
Before the first QuickBooks payroll, open your state withholding and unemployment accounts, collect W-4s and state forms, set…
READ MORE ●Business
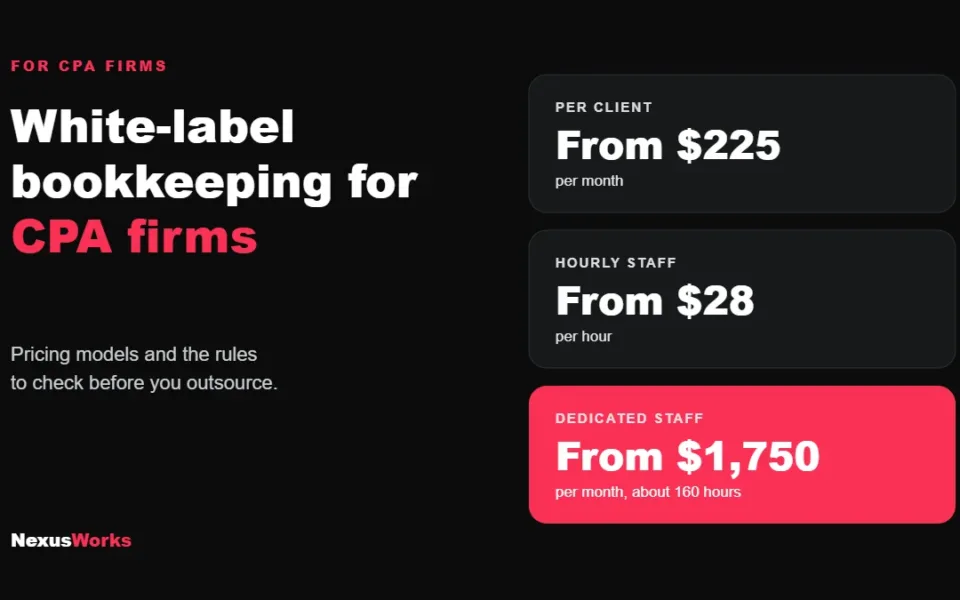
How white-label bookkeeping works for CPA firms, what it costs, and the Section 7216 and data security rules…
READ MORE ●Business
Get the exact wording from whoever is asking, then go to the CPA who prepares your returns with…
READ MORE ●Hi there! Have a question about tax, bookkeeping or CFO support? Send us a message on WhatsApp.
Start chat