Tax Planning Strategies
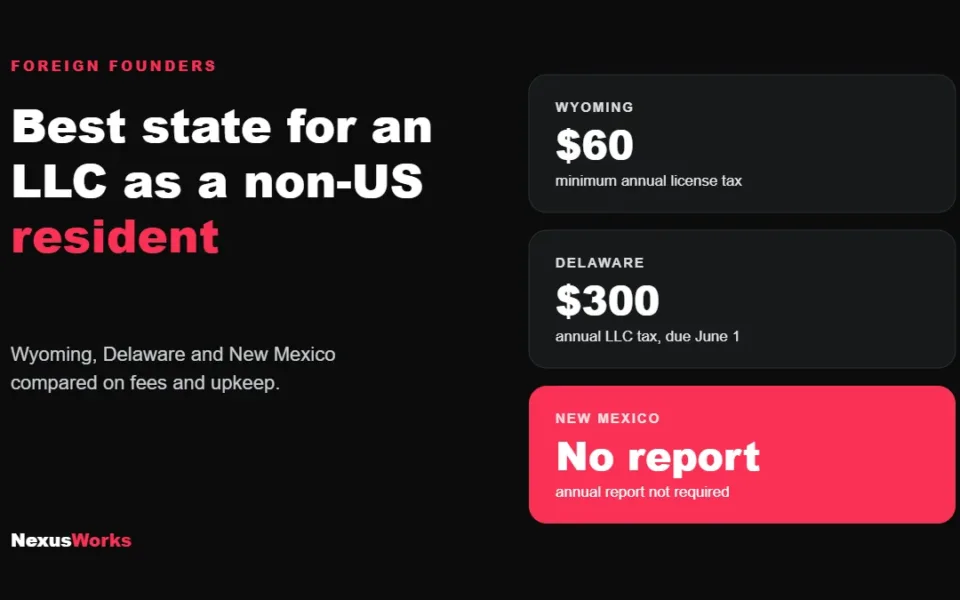
Best State to Form an LLC as a Non-US Resident
Wyoming is usually the best state for a non-US founder running an online business from abroad. Compare Wyoming,…
READ MORE ● NexusWorks Team
Reviewed by a licensed CPA
A W-2 gives you fewer levers than a business owner has, but the ones you have still matter. Consider maximizing your 401(k) and, if you’re eligible, your HSA; look at a backdoor Roth; close the withholding gap on RSUs and bonuses; bunch charitable gifts through a donor-advised fund; and time stock sales with care. In California, all of this income is also taxed at state rates, so timing counts.
This guide to tax planning for high-income earners walks through each lever, its 2026 limits and deadlines, and how California treats it differently. Most of these moves must be finished by your last paycheck or by December 31, so mid-November is the right time to look. If you’re unsure whether you need planning or just a well-prepared return, our guide to tax planning vs. tax preparation explains the difference.
Salary is ordinary income, withheld before you see it. Employees can’t choose a business structure, and most unreimbursed work expenses aren’t deductible. That’s why high earners often hear “there’s nothing you can do.”
High earners also stack several taxes on the same dollars. The top federal rate of 37% applies for 2026 above $640,600 of taxable income for single filers and $768,700 for married couples filing jointly. A 0.9% Additional Medicare Tax applies to wages above $200,000 ($250,000 joint), and the 3.8% Net Investment Income Tax can apply to investment income once modified adjusted gross income (MAGI) passes the same thresholds. California then adds rates of up to 13.3%.
Federal law changed for 2026. The federal state and local tax (SALT) deduction limit increases to $40,400 for 2026 ($20,200 for married individuals filing separately). However, the limit begins to phase down when MAGI exceeds $505,000 ($252,500 for married filing separately). The reduction equals 30% of MAGI above the applicable threshold, subject to a minimum deduction limit of $10,000 ($5,000 for married filing separately).
For California residents paying substantial state income and property taxes, the higher federal SALT limit may increase itemized deductions. However, the benefit depends on income, filing status and other itemized deductions.
So the levers are fewer, but they’re real, and most come down to timing.
| Lever | Who it suits | Deadline |
|---|---|---|
| 401(k) / 403(b) contributions (including catch-up) | Employees with a workplace plan and room left under the annual limit | Through payroll, by the last paycheck of the year |
| HSA contributions | People covered by an HSA-eligible high-deductible health plan | April 15, 2027 for 2026 (extensions don’t apply) |
| Backdoor Roth IRA | People above the Roth IRA income limits, ideally with little or no pre-tax IRA balance | Contribution by April 15, 2027; a conversion counts in the year it happens |
| RSU / bonus withholding adjustment | Employees with vesting RSUs, large bonuses or more than one job | Before the final paychecks of the year |
| Donor-advised fund contribution | Charitably inclined people who itemize, or could in a bunching year | Completed by December 31 |
| Timing stock sales / tax-loss harvesting | People with taxable brokerage accounts or concentrated company stock | Trade date by December 31 |
| Estimated tax payments | Anyone whose withholding won’t cover the year’s tax | Fourth installment due January 15, 2027 (federal and California) |
Whether a lever suits you depends on your income, employer plans, equity compensation, filing status and personal goals.
Want to review your withholding, RSUs and year-end options before December 31? Book a tax strategy call.
Pre-tax deferrals to a 401(k) or 403(b) reduce both your federal and California taxable wages. For 2026, the IRS limits are:
The big 2026 change for high earners is the Roth catch-up rule from SECURE 2.0. Beginning in 2026, employees whose 2025 FICA wages from the employer sponsoring their retirement plan exceed $150,000 must make eligible catch-up contributions on a Roth basis. These contributions are made with after-tax income rather than pre-tax salary deferrals, so they no longer reduce taxable wages.
This requirement applies to catch-up contributions, not the regular $24,500 employee deferral limit. If your employer’s plan does not offer a Roth contribution feature, your ability to make catch-up contributions may be affected. Confirm how your plan administrator is implementing the rule before adjusting your payroll elections.
Deferrals only happen through payroll, so the practical deadline is your final paycheck of the year. Some employers need several weeks to process an election change.
A Roth 401(k) is another option: no deduction now, but qualified withdrawals are tax-free later. The choice depends on your current rate versus your expected rate in retirement.
Some plans also allow after-tax (non-Roth) contributions above the deferral limit, which can then be converted to Roth inside the plan. This is often called a “mega backdoor Roth.” It is only available if your plan permits both features, and total contributions from all sources are capped at $72,000 for 2026 (catch-ups are additional).
A health savings account (HSA) is available only if you’re covered by an HSA-eligible high-deductible health plan and have no disqualifying coverage. For 2026, the limits are $4,400 for self-only coverage and $8,750 for family coverage, plus a $1,000 catch-up at age 55 or older. Contributions through payroll avoid federal income and FICA taxes. You can contribute for 2026 until April 15, 2027.
California note: California does not recognize HSAs. Contributions aren’t deductible for California, employer contributions are added back to California wages, and interest, dividends and gains inside the account are taxable for California each year. The federal benefit is real, but expect separate state tracking.
A backdoor Roth is a two-step process: you make a nondeductible contribution to a traditional IRA, then convert it to a Roth IRA. If you hold other pre-tax IRA money, the pro-rata rule makes part of the conversion taxable.
For 2026, direct Roth IRA contributions phase out between $153,000 and $168,000 of MAGI for single filers and $242,000 to $252,000 for joint filers. Conversions have no income limit, which is why the two-step approach is legal and widely used. The 2026 IRA contribution limit is $7,500, plus $1,100 at age 50 or older.
The pro-rata rule. The IRS treats all your traditional, SEP and SIMPLE IRAs as one pool, measured at December 31 of the year you convert. If that pool holds $67,500 of pre-tax money and you add $7,500 after-tax, about 90% of any conversion is taxable. Some people address this by rolling pre-tax IRA balances into an employer plan, if the plan accepts rollovers. Whether that makes sense depends on the plan and your situation.
You can contribute for 2026 until April 15, 2027, but timing matters: a conversion made in January 2027 is a 2027 event. See IRS Publication 590-A for the rules.
RSUs cause surprise tax bills because the shares are taxed as ordinary income when they vest, but employers usually withhold federal tax at a flat 22% supplemental rate. If your actual top rate is 32%, 35% or 37%, the difference becomes a balance due in April.
Under IRS Publication 15, supplemental wages such as bonuses and RSU income are generally withheld at 22% up to $1 million for the year. Above $1 million, a mandatory 37% applies. In California, the EDD’s supplemental rate for bonuses and stock options is 10.23%, below the state’s top rates of 12.3% and 13.3%.
The practical fixes:
Safe harbor. You generally avoid federal underpayment penalties by paying the smaller of 90% of this year’s tax or 100% of last year’s, or 110% if last year’s AGI exceeded $150,000 ($75,000 married filing separately). California uses similar rules, but if your California AGI is $1 million or more ($500,000 married filing separately), you must base payments on the current year’s tax. California’s installments are uneven: 30%, 40%, 0% and 30%, per the FTB’s 2026 Form 540-ES instructions.
Federal withholding is generally treated as paid evenly through the year, so extra withholding from a December paycheck can cover shortfalls from earlier quarters in a way a late estimated payment can’t. Confirm the California treatment with your advisor.
ESPPs and stock options follow different rules, and incentive stock options can trigger the alternative minimum tax (AMT) at exercise. Both deserve a professional review.
Want a second look at your RSU vests and withholding before the year closes? Book a tax strategy call.
Charitable bunching means grouping several years of planned donations into one tax year so your itemized deductions exceed the standard deduction, then taking the standard deduction in the years between.
A donor-advised fund (DAF) is a charitable account held by a sponsoring public charity. You contribute, generally take the deduction in the year of the contribution, and recommend grants to charities over later years. Donating long-term appreciated stock instead of cash can avoid capital gains tax on the appreciation and may allow a deduction for fair market value, generally limited to 30% of AGI.
Three 2026 federal changes affect the math, as described in IRS Publication 526:
California note: California doesn’t conform to these federal changes. It has its own itemized deduction rules, including a limit at higher incomes, and lets you itemize on your state return even if you take the federal standard deduction.
Contributions must be completed by December 31. Stock transfers can take days or weeks, so start early.
California taxes capital gains as ordinary income, with no lower rate for long-term gains. Federal rules are different, so timing can matter more for your federal return than your state return.
These are tax considerations, not investment advice. Decisions to buy, sell or hold belong with a qualified financial advisor who can weigh risk and diversification.
Residency rules are complex, and any move should be reviewed with a professional first.
| Area | CPA | Financial advisor |
|---|---|---|
| Focus | Tax projections, withholding analysis, estimated payments, reporting | Investment selection, portfolio allocation, diversification |
| Equity compensation | Tax treatment of RSUs, ESPPs and options | Whether to hold or sell, and how to reinvest |
| Retirement and giving | Contribution coordination, charitable timing, Form 8606 | Account investments and long-term planning |
Many high earners benefit from both working together. NexusWorks provides tax planning, not investment advice.
NexusWorks is led by California-licensed CPAs. Our tax planning and strategy services include tax projections, year-end planning and estimated tax payment setup. A clearly scoped planning engagement for a high-income employee generally follows these steps:
We confirm scope before work begins and can’t promise a particular outcome. Related services include tax filing and compliance and financial advisory and optimization. You can also learn more about NexusWorks.
A preparation aid for a year-end planning conversation, not a plan.
☐ Year-to-date pay stubs and withholding (federal and California)
☐ RSU, ESPP and option vesting schedules
☐ Expected bonus amount and timing
☐ 401(k) contributions to date and catch-up status
☐ HSA eligibility and contributions to date
☐ Year-end balances of all traditional, SEP and SIMPLE IRAs
☐ Planned charitable gifts for this year and next
☐ Unrealized gains and losses in taxable accounts
☐ Estimated payments made (federal and California)
☐ Prior-year federal and California returns
☐ Deadlines and notes: ______________________
Yes, though the options are narrower than for business owners. The main levers are pre-tax retirement and HSA contributions, a backdoor Roth, fixing withholding on RSUs and bonuses, charitable bunching through a donor-advised fund, and timing stock sales. Most depend on acting before your last paycheck or December 31.
For 2026, the 401(k) employee deferral limit is $24,500, with an $8,000 catch-up at age 50 or older, or $11,250 at ages 60 to 63 if the plan allows. The IRA limit is $7,500, plus $1,100 at 50 or older. Check the IRS for any updates.
Yes. Conversions have no income limit, so contributing to a nondeductible traditional IRA and converting it is a recognized approach. It must be reported on Form 8606, and the pro-rata rule can make part of the conversion taxable if you hold other pre-tax IRA balances.
RSUs are taxed as ordinary income at vesting, but employers usually withhold at a flat 22% federal supplemental rate and 10.23% in California. If your actual rates are higher, the difference shows up as a balance due. Adjusting withholding or making estimated payments can close the gap.
No. California does not recognize HSAs, so contributions aren’t deductible on your California return, employer contributions are added to state wages, and interest, dividends and gains are taxable for California each year. The federal deduction still applies if you’re covered by an HSA-eligible plan, so keep separate records.
Your W-2 sets most of your income, but it doesn’t set every decision. Retirement deferrals, withholding, charitable timing and stock sales can all still change how this year ends. If any of them apply to you, review them before your final paychecks and December 31 with a qualified advisor.
Want to review your withholding, RSUs and year-end options before December 31? Book a tax strategy call.
You can also contact NexusWorks to discuss your situation.
Keep reading
Tax Planning Strategies
Wyoming is usually the best state for a non-US founder running an online business from abroad. Compare Wyoming,…
READ MORE ●Tax Planning Strategies
An LLC taxed as an S corp in California usually pays off once profit passes about $80,000 to…
READ MORE ●Tax Planning Strategies
Compare fractional CFO vs. full-time CFO costs, responsibilities and benefits. Learn when each option makes financial sense for…
READ MORE ●Hi there! Have a question about tax, bookkeeping or CFO support? Send us a message on WhatsApp.
Start chat