Tax Planning Strategies
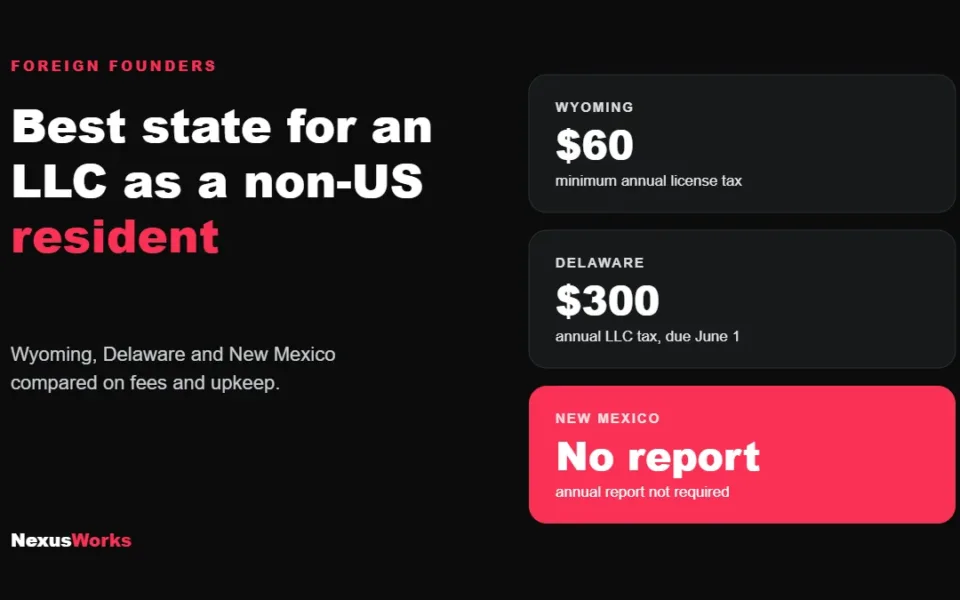
Best State to Form an LLC as a Non-US Resident
Wyoming is usually the best state for a non-US founder running an online business from abroad. Compare Wyoming,…
READ MORE ● NexusWorks Team
Reviewed by a licensed CPA
Short answer: An LLC taxed as an S corp in California usually pays off once profit passes about $80,000 to $100,000. See the real math, the costs and the deadline.
Short answer: in California, an LLC taxed as an S corporation usually starts to pay off once the business clears about $80,000 to $100,000 a year in profit and the owner can take a reasonable salary through payroll. Below that, the extra payroll, the separate return and California’s 1.5% franchise tax tend to eat most of the savings. Above it, the savings on self-employment tax grow quickly.
That’s the rule of thumb. The rest of this article shows the actual math at three profit levels, the California costs most comparisons leave out, and the timing that decides whether the election works for this year or next.
This question confuses a lot of owners because the two aren’t the same kind of thing. An LLC is a legal entity you form with the California Secretary of State. An S corporation is a tax status you ask the IRS for. Most small businesses that “become an S corp” stay an LLC on paper and file Form 2553 to be taxed as an S corporation.
So the real choice is between two ways of taxing the same business:
That gap in payroll tax is the whole reason the S corp exists as a strategy. Everything else is cost.
| LLC (default taxation) | LLC taxed as an S corp | |
|---|---|---|
| California minimum tax | $800 annual tax | $800 minimum franchise tax |
| California tax on profit | None at the entity level | 1.5% of net income, if that’s more than $800 |
| Gross receipts fee | $900 to $11,790 once California income passes $250,000 | Doesn’t apply |
| Federal return | Schedule C on your personal return | Separate Form 1120-S, plus a K-1 to each owner |
| California return | Form 568 | Form 100S |
| Payroll | Not required for the owner | Required: quarterly federal and EDD filings, W-2 at year end |
| Self-employment tax | 15.3% on about 92% of all profit | 15.3% on the salary only |
The $800 and the fee schedule come from the Franchise Tax Board’s LLC page. The first-year exemption from the $800 only covered tax years starting in 2021 through 2023, so new LLCs pay it from year one again. We break the LLC side down in our California LLC $800 tax and Form 568 guide.
One detail that often gets missed: the LLC gross receipts fee is based on total California income, not profit. A business with $600,000 in sales and a thin margin still owes the $2,500 fee as a regular LLC. Once the LLC is taxed as an S corporation, it pays the 1.5% franchise tax instead and that fee drops away. For some higher-revenue businesses, that switch alone covers part of the extra cost.
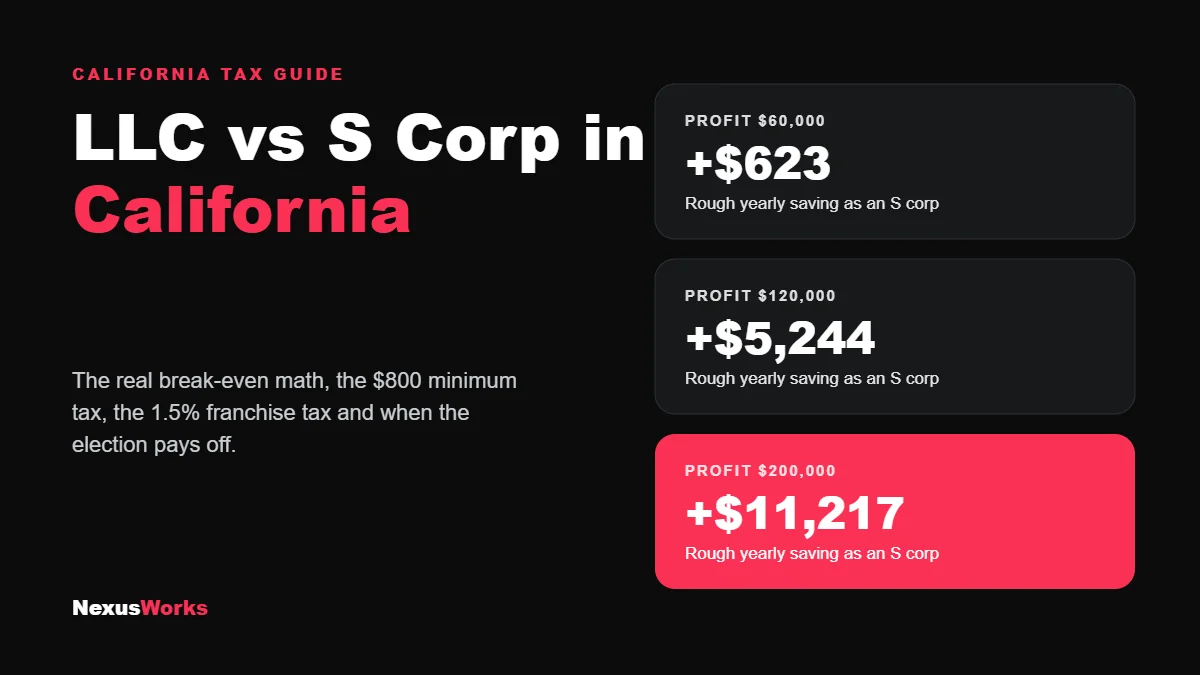
Here’s a single-owner California business at three levels of net profit. The S corp column assumes a reasonable salary for each level and about $2,500 a year in extra costs for payroll processing, the 1120-S, the 100S and California unemployment tax on the first $7,000 of wages. Your own numbers will differ, but the pattern holds.
| Net profit | $60,000 | $120,000 | $200,000 |
|---|---|---|---|
| Owner salary in the S corp | $35,000 | $60,000 | $90,000 |
| Self-employment tax as an LLC | $8,478 | $16,955 | $28,234 |
| Payroll tax on the salary | $5,355 | $9,180 | $13,770 |
| Payroll tax saved | $3,123 | $7,775 | $14,464 |
| Extra California franchise tax | $0 | $31 | $747 |
| Extra admin and payroll costs | $2,500 | $2,500 | $2,500 |
| Rough net saving | $623 | $5,244 | $11,217 |
A few notes on how we got there:
At $60,000, the election mostly trades one bill for another. At $120,000 it’s worth doing. At $200,000 it’s hard to justify staying a default LLC.
The savings above only hold up if the salary is defensible. The IRS says an S corporation has to pay a shareholder who works in the business reasonable compensation before taking distributions, and it can reclassify distributions as wages if the salary is too low. Its guidance on S corporation compensation lists the factors that matter, including your training, your duties, the time you put in and what comparable businesses pay for the same work.
In practice, that means a consultant billing $150,000 of their own hours can’t pay themselves $25,000 and call the rest a distribution. Where the profit comes from your personal work, more of it has to be salary. Where it comes from employees, equipment or capital, more can come out as distributions. We’ve seen this play out in detail for clinic owners in our article on reasonable compensation for medical and dental owners.
A single-owner LLC taxed as a sole proprietorship can’t use California’s pass-through entity elective tax. An S corporation can. The PTE tax lets the business pay 9.3% California tax on qualified income at the entity level, which helps owners get around the federal limit on deducting state taxes, and the owner gets a matching California credit.
The FTB’s PTE elective tax page says the election now runs for tax years through 2030. From 2026, a missed or short June 15 payment no longer kills the election, but it does reduce the credit. For a profitable S corp owner in a high bracket, this can be worth more than the payroll tax savings. We cover the numbers in whether the California PTE tax is worth it in 2026.
To be an S corporation for the whole of a calendar year, the IRS generally needs Form 2553 no later than 2 months and 15 days after the year starts, which is March 15. A brand new LLC has 2 months and 15 days from the date it starts business. Miss it and the election usually starts the following year, although late election relief exists if you have reasonable cause.
Before you file, have three things ready:
Our QuickBooks payroll setup checklist covers the payroll side step by step.
An 1120-S return for one state starts from $650. Monthly bookkeeping starts from $199 a month, and our Formation Growth package at $795, plus state fees, is built for owners who plan to run payroll or make the S corp election from the start. The full list is on our pricing page, and our tax planning team can run your own numbers before you decide.
It depends on profit. An LLC taxed as an S corp usually saves money once profit passes roughly $80,000 to $100,000 and the owner takes a reasonable salary. Below that, extra payroll and filing costs often cancel out the savings.
Yes. An eligible LLC files Form 2553 with the IRS to be taxed as an S corporation. It stays an LLC legally, but it files Form 1120-S federally and Form 100S in California.
Yes. An S corporation pays 1.5% of its California net income or the $800 minimum franchise tax, whichever is higher. It doesn’t pay the separate LLC gross receipts fee.
Enough to match what the business would pay someone else for the work you do. The IRS looks at your duties, experience, hours and what similar businesses pay. A salary set too low can be reclassified as wages, with back payroll taxes and penalties.
For a calendar year business, Form 2553 is generally due by March 15 for the election to cover that whole year. A new business has 2 months and 15 days from when it starts.
Not sure which side of the line your business falls on? Book a consultation with last year’s profit and loss, and we’ll run both scenarios with your real numbers before you file anything.
Keep reading
Tax Planning Strategies
Wyoming is usually the best state for a non-US founder running an online business from abroad. Compare Wyoming,…
READ MORE ●Tax Planning Strategies
Compare fractional CFO vs. full-time CFO costs, responsibilities and benefits. Learn when each option makes financial sense for…
READ MORE ●Tax Planning Strategies
Tax preparation reports the year; tax planning shapes it. See which decisions must happen before December 31 and…
READ MORE ●Hi there! Have a question about tax, bookkeeping or CFO support? Send us a message on WhatsApp.
Start chat