Tax Planning Strategies
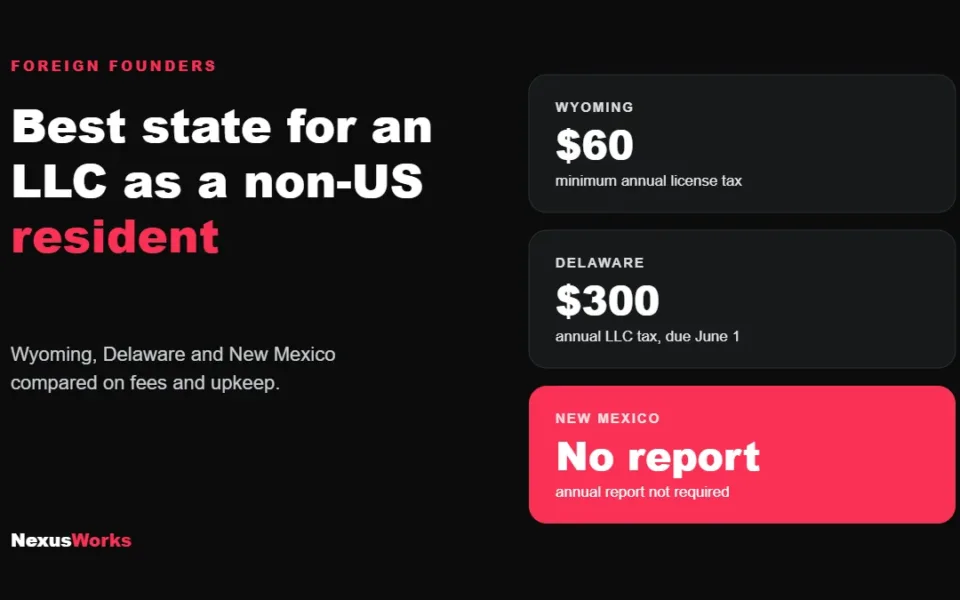
Best State to Form an LLC as a Non-US Resident
Wyoming is usually the best state for a non-US founder running an online business from abroad. Compare Wyoming,…
READ MORE ● NexusWorks Team
Reviewed by a licensed CPA
Short answer: A foreign-owned single-member LLC files Form 5472 attached to a pro forma Form 1120. It can't be e-filed. Fax it to 855-887-7737 or mail it to the IRS PIN Unit in Ogden, Utah, by April 15, or by October 15 if you file Form 7004 first.
Most foreign owners of a US single-member LLC learn about Form 5472 the hard way: a friend mentions the $25,000 penalty, or a bank asks whether the LLC filed anything with the IRS last year. The form itself is short. The filing process is what trips people up, because it does not work like a normal US tax return. You can’t e-file it, it goes to a special IRS unit in Ogden, Utah, and it has to sit on top of a mostly blank Form 1120.
This guide walks through the filing itself, step by step. If you’re still working out whether your LLC needs to file at all, start with our article on who must file Form 5472 and how the penalty works, then come back here.
A foreign-owned single-member LLC is a “disregarded entity” for US income tax. It normally files nothing on its own. The IRS makes an exception for reporting: the LLC is treated as a corporation for Form 5472 purposes, so it files two documents together:
Both pages go in as one package. The IRS instructions ask you to write “Foreign-owned U.S. DE” across the top of the Form 1120.
Collect these before you open a single form. Missing any one of them is the usual reason a filing stalls in March.
| Item | Where it comes from |
|---|---|
| LLC’s EIN | IRS confirmation letter CP 575. Without an EIN the LLC cannot file. |
| Owner’s foreign tax ID or US ID | Passport country tax number, or an ITIN or SSN if the owner has one |
| Owner’s address and country of citizenship, organization or residence | Owner records |
| Total assets at year end (Form 5472, line 1c) | LLC bank statements and any other assets the LLC holds |
| Every transfer between the owner and the LLC | Bank statements: capital put in, money taken out, loans, payments for services, formation costs paid by the owner |
That last row matters most. Money the owner sends in to open the bank account is a reportable transaction. So is the $300 the owner paid personally to form the LLC, and so is every draw back to the owner’s own account. Many first-time filers report nothing because the LLC “didn’t make money”, and that’s the mistake the penalty is built to catch.
Not sure about the ID numbers? Our guide to EIN vs ITIN for foreign business owners explains which one the owner needs.
Use the Form 1120 for the year you’re reporting. Fill in only:
Write “Foreign-owned U.S. DE” across the top of page one. Leave the income and deduction lines blank. The owner (or an authorized officer) signs it.
Form 5472 has seven parts. A typical single-owner LLC uses four of them.
Use full dollar amounts. Reasonable estimates are allowed in some cases under the instructions, but a guess with no records behind it is not a reasonable estimate.
This is where foreign-owned LLCs differ from everyone else. According to the IRS Instructions for Form 5472, a foreign-owned US DE cannot file Form 5472 electronically. You have two options:
Do not use the Form 1120 mailing addresses. They’re for regular corporations, and a 5472 package sent there can sit in the wrong pile while the deadline passes. Keep the fax confirmation page or a tracked courier receipt. If the IRS ever says it never arrived, that proof is your best defense.
For an LLC on a calendar year, the package is due April 15. The LLC uses the same tax year as its owner for US purposes, or the calendar year if the owner has none.
If you need more time, file Form 7004 by April 15. That gives an automatic six months, so the new deadline is October 15. Three details make the extension valid:
An extension gives you more time to file. It doesn’t fix a filing that was due in an earlier year.
The IRS charges nothing to file. The cost is preparation. At NexusWorks, a Form 5472 with the pro forma 1120 starts from $350 per year, and the price goes up with the number of transactions and whether earlier years need catching up. You can see the full list on our pricing page. Non-US founders who want formation, the EIN and this filing handled together usually choose the Global Founder package on our company formation page.
Don’t wait for a letter. File the missing years as soon as the records are rebuilt, each one complete and on its own pro forma 1120. A late but complete filing, together with a clear explanation, is a far better starting point than an IRS notice that arrives first. Depending on the facts, a penalty abatement request may be possible. That’s a judgment call for a CPA who has seen the bank statements, not something to try from a template.
No. The IRS instructions say a foreign-owned US disregarded entity cannot file Form 5472 electronically. It has to be faxed to 855-887-7737 or mailed to the PIN Unit in Ogden, Utah.
Usually yes. The form reports transactions with the owner, not income. Putting money into the LLC, paying its formation costs or taking money out are all reportable, even in a year with zero sales.
File Form 7004 by April 15 using the Form 1120 code, write “Foreign-owned U.S. DE” at the top, and fax or mail it to the same Ogden unit. The deadline moves to October 15.
$25,000 for each year a required form is not filed on time and in the right manner. A substantially incomplete form counts as not filing, and more penalties can follow if the failure continues after an IRS notice.
Want this done correctly the first time? Book a call with our team and bring your LLC’s bank statements. We’ll tell you exactly what needs to be reported and by when.
Keep reading
Tax Planning Strategies
Wyoming is usually the best state for a non-US founder running an online business from abroad. Compare Wyoming,…
READ MORE ●Tax Planning Strategies
An LLC taxed as an S corp in California usually pays off once profit passes about $80,000 to…
READ MORE ●Tax Planning Strategies
Compare fractional CFO vs. full-time CFO costs, responsibilities and benefits. Learn when each option makes financial sense for…
READ MORE ●Hi there! Have a question about tax, bookkeeping or CFO support? Send us a message on WhatsApp.
Start chat